When to Sell a Condo in Miami-Dade, Broward & Palm Beach
A data-driven guide to condo seasonality, selling speed, inventory, and market conditions across South Florida’s three counties, so you can choose the best time to list and maximize your results.
Quick answer: when is the best time to sell a condo in South Florida?
List in spring — roughly April through June — for the shortest time to contract. Based on 2020–2025 condo sales, the median days on market is about 36 days in spring versus 42–44 days in January–February (~20% faster).
Seasonality is real but moderate. Building-specific conditions, correct pricing, and current inventory can have a greater impact on your result than the month you choose — especially in today’s high-supply market.
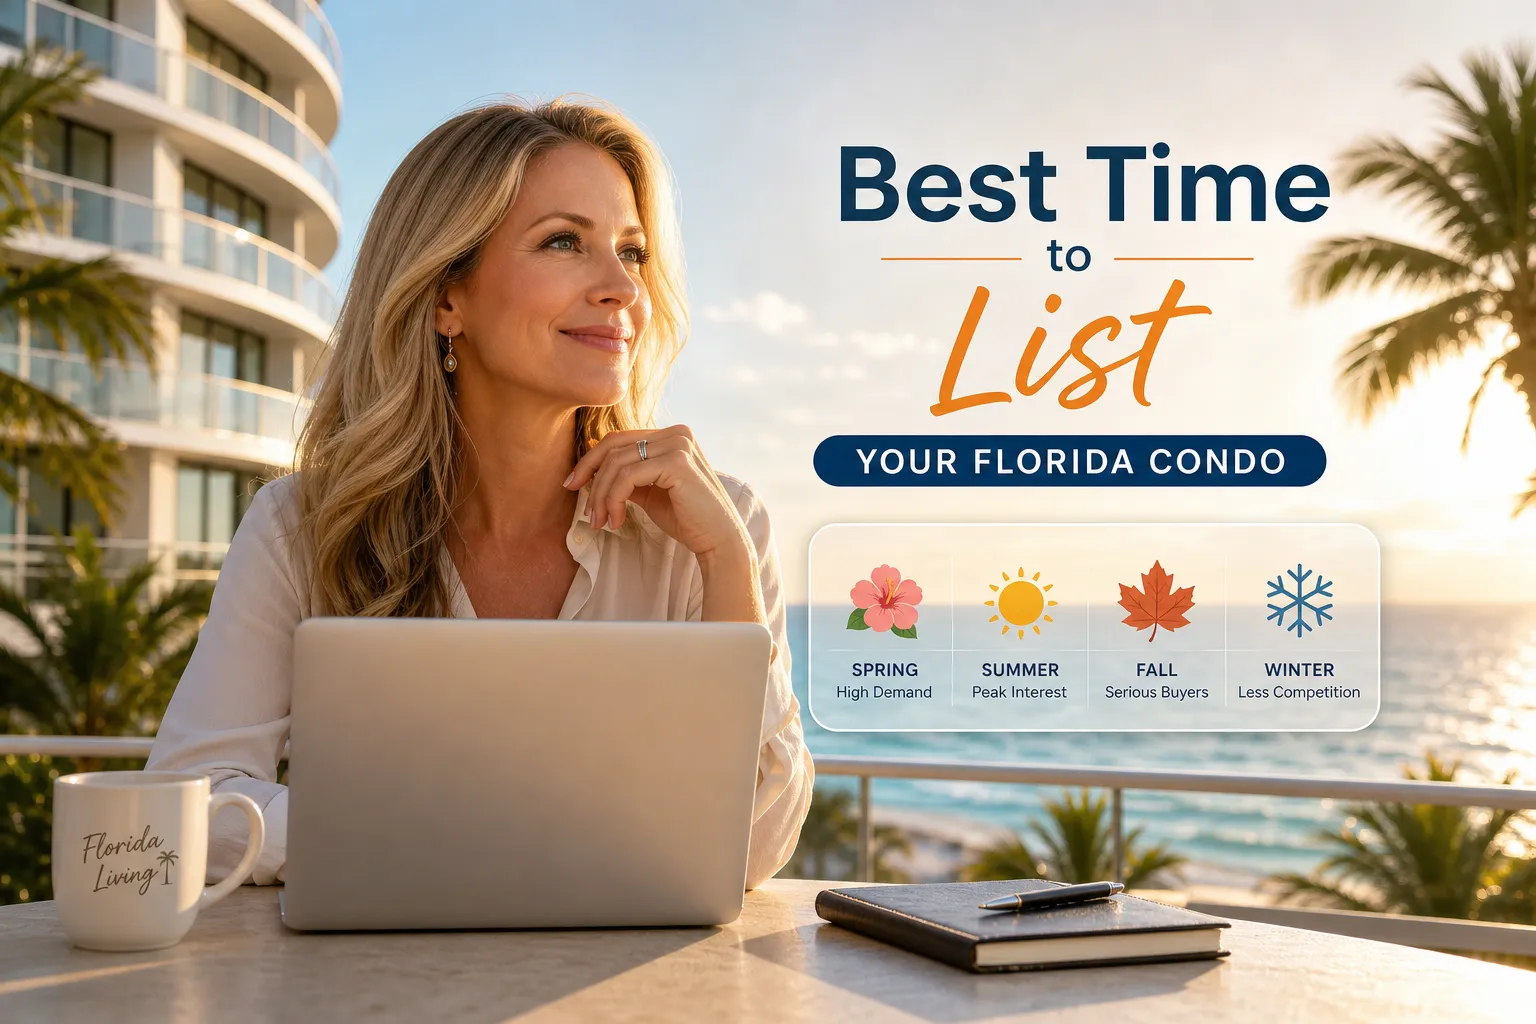
South Florida condo selling calendar
A seasonal overview of listing activity, buyer demand, and selling speed in Miami-Dade, Broward and Palm Beach.
Highest Activity
Most new listings and buyer activity.
Fastest Sales
Shortest time to contract (~36 days).
Lower Demand
Fewer buyers and a slower pace.
Building Season
Listings thin out; demand builds toward Q1.
South Florida condo market seasonality (sales only)
Monthly average for Miami-Dade, Broward and Palm Beach, 2020–2025 (six complete years). Leases are excluded.
Source: AndresJara MLS analysis (RESO feed). Condominium sales only, three counties, average of six complete years 2020–2025. Days on market = median list-to-contract. This is the historical seasonal pattern — current-market days on market are higher (see snapshot below).
The single highest month for closed sales is March, reflecting contracts signed during the winter buyer season. Summer is not the peak for closings.
| Month | New listings (avg/mo) | Closed sales (avg/mo) | Median DOM |
|---|---|---|---|
| January | 3,632 | 2,362 | 42 |
| February | 3,310 | 2,661 | 44 |
| March | 3,349 | 3,732 | 39 |
| April | 2,845 | 3,482 | 36 |
| May | 2,975 | 3,269 | 36 |
| June | 2,971 | 3,207 | 36 |
| July | 2,817 | 2,975 | 37 |
| August | 2,876 | 2,878 | 36 |
| September | 2,853 | 2,687 | 38 |
| October | 3,007 | 2,752 | 39 |
| November | 2,802 | 2,506 | 40 |
| December | 2,587 | 2,841 | 41 |
South Florida condo market snapshot
Trailing 12 months, condo sales only. These are current conditions — distinct from the historical seasonal averages in the chart above.
| County | Median sale price | Median $/SF | Active listings | Closed sales | Months of supply | Median DOM | YoY price |
|---|---|---|---|---|---|---|---|
| Miami-Dade | $400,000 | $408 | 15,958 | 9,148 | 20.9 | 76 | 0.0% |
| Broward | $210,000 | $205 | 12,602 | 8,778 | 17.2 | 71 | −4.5% |
| Palm Beach | $255,000 | $219 | 7,691 | 7,715 | 12.0 | 63 | 0.0% |
Current median days on market (63–76) runs well above the 36–44 day historical seasonal average because inventory is elevated across all three counties. Months of supply = active listings ÷ (trailing-12-mo closed sales ÷ 12).
A closer look at each season
Highest activity, more competition
The peak season for new listings and buyer activity, driven by snowbirds and international demand. Because the most inventory arrives at once, expect more competition and a slightly longer time to contract (42–44 days in January–February). Launch early and priced right to stand out.
The best window for speed
As the winter inventory wave is absorbed, competition eases while serious buyers remain. Median time to contract bottoms out around 36 days — the fastest of the year — and March produces the most closings as winter contracts settle.
Lower demand, longer timelines
Buyer activity eases from the spring peak and inventory remains high, so plan for a modestly longer time to contract (37–38 days). Hurricane season adds friction: when a named storm is forecast, insurers pause binding, which can delay a financed closing.
Activity builds for winter
New-listing volume thins into the holidays — December is the quietest listing month — so there’s less competition, and the buyers who are active tend to be motivated. Momentum then builds back toward the Q1 peak.
County-by-county analysis
The three counties sit at different price points and different stages of the current buyer’s market. Condo sales only, trailing 12 months.
The highest condo prices and the deepest inventory overhang (~21 months), with a current median of 76 days to contract and flat prices year over year. The county spans very different sub-markets — luxury coastal towers in Miami Beach, Sunny Isles Beach and Bal Harbour; the new-construction core of Brickell, Downtown and Edgewater; and value-oriented inventory in Aventura and North Miami Beach. Here, pricing to your specific building and line matters more than the calendar. See the Miami-Dade hub, Brickell overview and Aventura guide.
The entry point of the three, with a median near $210,000 and the softest pricing — down about 4.5% year over year. Inventory is high (~17 months) but a step below Miami-Dade. Demand concentrates in beachfront Fort Lauderdale and Hollywood, high-rise Hallandale Beach, and Pompano Beach. With prices easing, sharp pricing and a clean building story are especially important. See the Broward hub, Fort Lauderdale guide and Hallandale Beach guide.
The healthiest balance of the three: the lowest months of supply (~12) and the fastest median time to contract (63 days), with prices holding flat. Demand concentrates in Boca Raton, West Palm Beach, Delray Beach and Boynton Beach. Sellers here have modestly more leverage — though 12 months of supply is still a buyer-leaning market. Explore the Palm Beach hub.
Condo-specific selling considerations
In South Florida these building-level factors often move your sale more than the season. General information — verify specifics with your attorney, association and lender.
Milestone inspections (SB 4-D)
Buildings of three or more habitable stories must complete a milestone structural inspection at 30 years from the certificate of occupancy (as early as 25 near the coast where required), then every 10 years. A pending or adverse inspection affects buyer confidence and financing.
Structural Integrity Reserve Studies (SIRS) & reserves
Associations existing on or before 7/1/2022 were required to complete a SIRS by December 31, 2025, and reserves for SIRS structural items can no longer be waived. HB 913 (eff. 7/1/2025) raised the reserve-study cost threshold from $10k to $25k. Well-funded reserves are a selling point.
Special assessments & financing eligibility
An active or looming special assessment, deferred repairs, or thin reserves can make a building non-warrantable to Fannie Mae/Freddie Mac — shrinking your buyer pool to cash and portfolio lenders. Know your building’s financing status before you price.
Insurance & building risk
Insurance cost and availability vary sharply by building age, construction and claims history, and carriers suspend binding when a named storm is forecast — a reason some sellers aim to be under contract before peak storm weeks.
Pricing vs. competing inventory
With 12–21 months of supply, buyers compare your unit directly against others for sale in your building and line. Price to the live comp set using $/SF for your tier — not a county average — and account for how quickly your building actually absorbs listings.
Find your condo building
See building-specific performance, recent sales, inventory, and a personalized selling strategy.
Seller preparation checklist
Analyze My Building
Historical seasonality, competition and pricing for your exact condo.
Discover My Condo’s Value
A data-backed estimate of what your unit could sell for today.
Personalized Selling Strategy
A timing, pricing and competition plan from Andres.
Frequently asked questions
What is the best month to list a condo in South Florida?
For the fastest sale, spring — April through June — when median days on market bottom out around 36 across Miami-Dade, Broward and Palm Beach. January through March brings the most buyers (snowbird season) but also the most competing listings, so time-to-contract is slightly longer (42–44 days). Pricing and your building’s condition still matter more than the month.
How long does it take to sell a condo in South Florida right now?
In the current market the median time to go under contract is about 63 days in Palm Beach, 71 in Broward, and 76 in Miami-Dade — slower than the 36–44 day seasonal average of 2020–2025, because inventory is high. Then allow roughly 30–45 more days to close a financed sale.
Which month has the most condo closings?
March. It is the single highest month for closed sales in the 2020–2025 data, reflecting contracts signed during the winter buyer season. Summer is not the peak closing season.
Do condos sell for more in a particular season?
This analysis measures selling speed and volume by season, not seasonal differences in sale price, so we don’t claim a seasonal price premium either way. The year-over-year county figures reflect the annual price trend, not seasonality. What the data clearly shows is that season affects how quickly you sell and how many buyers are active more than it affects headline price.
Why does my building matter more than the calendar?
South Florida condo inventory is roughly 12–21 months of supply depending on the county. In a market that oversupplied, a well-priced unit in a healthy, warrantable building can sell in most months, while an overpriced unit in a building with assessments or reserve problems can sit regardless of season.
Research methodology & data sources
Market data. AndresJara MLS analysis (RESO feed). Condominium sales only (PropertyType = Residential, PropertySubType = Condominium); closed and active leases are excluded. Geography: Miami-Dade, Broward & Palm Beach counties.
Periods & definitions. County snapshot = trailing 12 months vs. prior 12 months. Seasonality = average per calendar month across six complete years 2020–2025 (partial 2019 and 2026 excluded to avoid year-coverage bias). Median sale price from closed ClosePrice; $/SF = ClosePrice ÷ LivingArea (≥300 sf); days on market = median list-to-contract. Months of supply = active for-sale listings ÷ (trailing-12-month closed sales ÷ 12); cross-checked against a 90-day-annualized pace (≈24 / 20 / 14 months) and pending-to-active ratios (≈8–9%).
Limitations. Active inventory is a current snapshot; all figures are historical and descriptive, not forecasts or causal claims. Seasonal differences in sale price were not separately modeled. Statewide Florida figures are not used — this is three-county condo data only. Legal and financial items summarize Florida SB 4-D / HB 913 and DBPR condominium resources plus lending-industry reporting; general information, not legal or lending advice.
Get a Personalized Selling Strategy for Your Condo
A data-driven plan for your condo, including optimal timing, pricing insights, and a review of current competition in your building.