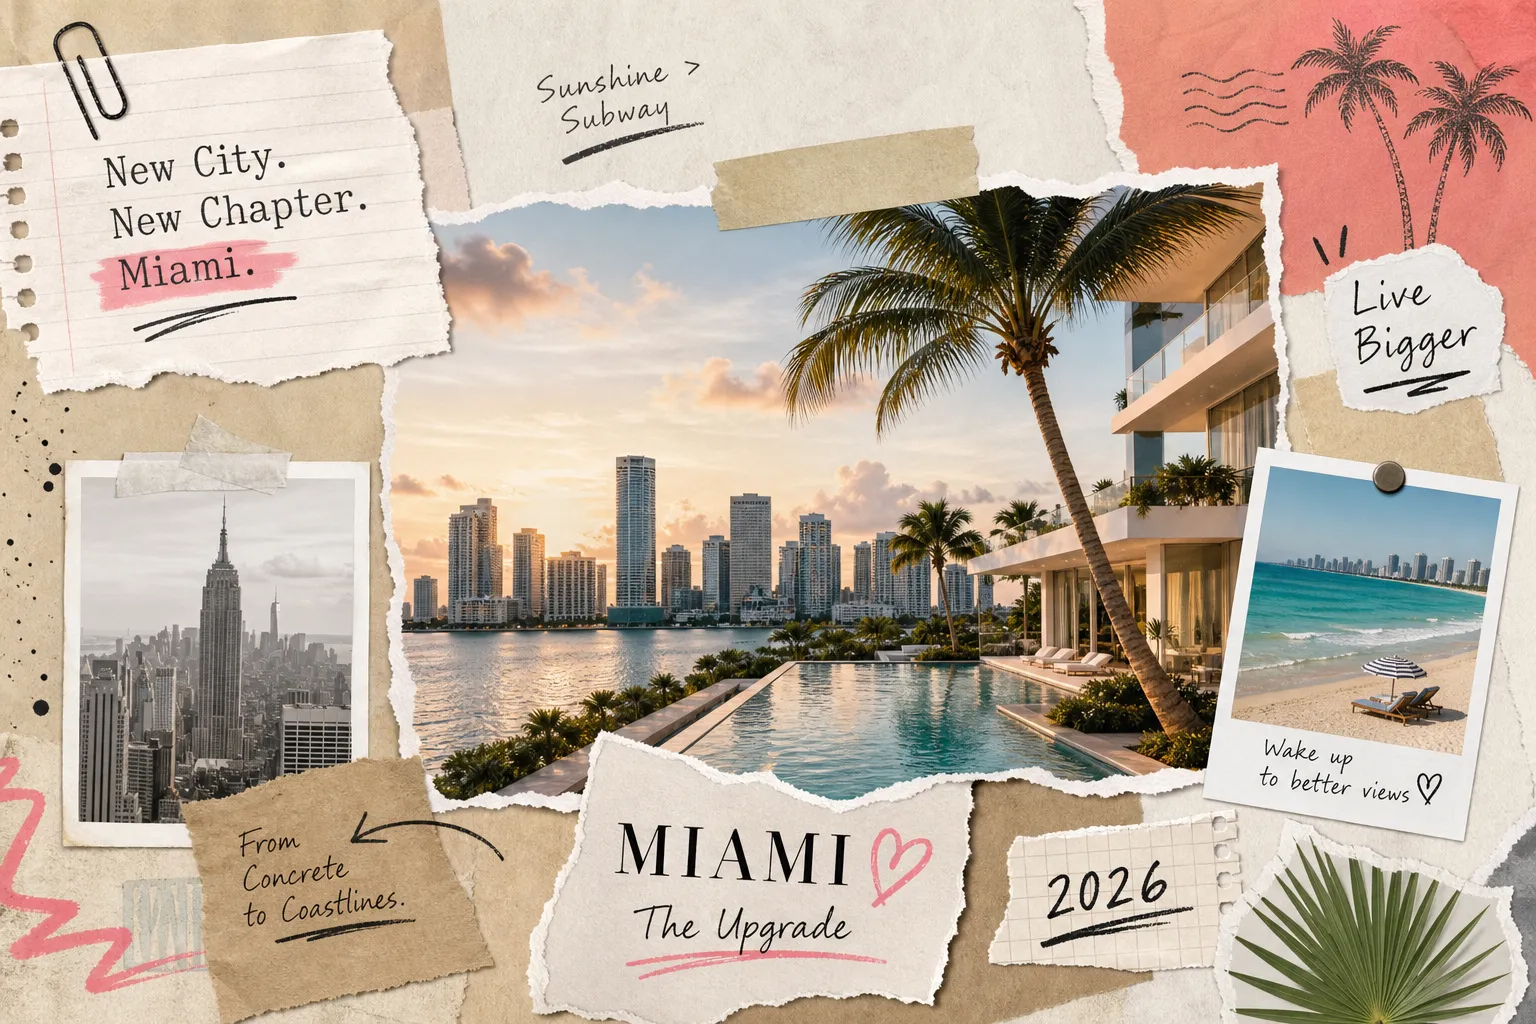
Miami luxury real estate for New Yorkers represents one of the most compelling financial repositions available in 2026, and the numbers make the case before a single showing. Manhattan luxury condos trade at a steep premium per square foot, often two to three times what comparable Miami luxury commands. At the same $5 million budget, a New Yorker gets dramatically more square footage, direct waterfront access in many buildings, and zero Florida state income tax. That gap is not marketing language; it is what 2026 closed-sale data confirms.
This guide gives you the exact playbook: neighborhood comparisons matched to New York lifestyle profiles, a full breakdown of recurring ownership costs, financing terms for out-of-state buyers, realistic relocation budgets, and a clear path to close with confidence. The building-level detail in each section reflects the kind of granular research that separates informed buyers from those who overpay in a market they only half-understand.
Key takeaways
- Price gap is real: Miami luxury condos close at a fraction of Manhattan’s per-square-foot pricing, giving buyers substantially more space per dollar.
- Neighborhoods match NYC profiles: Many major New York lifestyle segments have close South Florida analogues, from Brickell for finance professionals to Coral Gables for Upper East Side buyers.
- Insurance is the wildcard: Waterfront homes can carry $15,000–$35,000 or more in annual premiums; this requires due diligence, not avoidance.
- Financing is accessible: New York residency is not an obstacle; lenders focus on property type, occupancy, income, and reserves.
- Tax savings are decisive: New York’s combined state and city income tax can reach nearly 15% for top earners; Florida has none.
- Relocation costs add up: A full-service family relocation runs $25,000–$50,000 before legal and tax planning.
How does Miami luxury pricing compare to Manhattan?
The price-per-square-foot gap between these two markets is wide enough to change a buyer’s entire financial calculus. Brickell luxury condos close well below Manhattan pricing on a per-square-foot basis, and even Sunny Isles Beach oceanfront luxury, with trophy towers like the Porsche Design Tower and Ritz-Carlton Residences at the top of the range, trades at a meaningful discount to comparable Manhattan product.
Brickell vs. Midtown Manhattan: price per square foot side by side
MarketRelative luxury pricingWhat $5 million buysBrickell (luxury resales)Well below ManhattanA large high-floor condo in a full-amenity building, several thousand square feetSunny Isles Beach (oceanfront luxury)A fraction of Manhattan per sq. ft.A spacious residence with direct Atlantic frontage and resort amenitiesManhattan luxury condosTwo to three times Miami pricingA far smaller unit, typically no outdoor space, high common charges
Sunny Isles Beach: oceanfront access at a fraction of the Manhattan cost
Sunny Isles delivers direct Atlantic frontage at pricing that would not buy a non-waterfront unit in most of Midtown. For buyers who prioritized oceanfront access in New York, this comparison tends to close the argument. In practice, inventory entering 2026 remained tighter than the pre-2022 surge years, though absorption rates in Sunny Isles have moderated on older product, buyers with strong qualifications often find meaningful negotiating room on resales in buildings completed before 2020, particularly when days-on-market data for a specific tower supports that position.
Miami luxury real estate for New Yorkers: neighborhood matches by lifestyle
Not every New York buyer wants the same thing. The right South Florida submarket depends on whether walkability, school quality, beach access, or privacy matters most to your household. Several distinct buyer profiles account for the majority of relocating New Yorkers, and each maps cleanly to a Miami submarket.
For the finance professional: Brickell and Edgewater
Brickell is Miami’s most Manhattan-adjacent neighborhood: high-density, walkable, with private elevator access, concierge amenities, and a concentration of financial offices that makes a work-from-Miami arrangement genuinely functional. A buyer coming from Midtown or the Financial District will recognize the rhythm immediately. Edgewater offers a residential alternative with Biscayne Bay views at a slightly lower per-square-foot cost on many resales, and faster access to the Design District and Wynwood. For NYC buyers evaluating Miami luxury condos as a primary base, Brickell remains the default starting point.
For the Upper East Side buyer: Coral Gables
Coral Gables matches the Upper East Side’s quieter register almost exactly: refined Mediterranean architecture, tree-lined streets, top-tier private schools, and a polished dining scene built for adults rather than tourists. Luxury homes here start around $1.2–$1.5 million and climb well beyond that for renovated estates on larger lots. The neighborhood’s established character and walkable Miracle Mile retail corridor make it well-suited to buyers who want residential permanence, not a party scene. Among South Florida luxury estates, Coral Gables consistently draws buyers making a full New York to Miami relocation rather than a seasonal purchase.
For families seeking space and schools: Coconut Grove, Pinecrest, and Key Biscayne
Coconut Grove delivers waterfront access, a village energy, and proximity to Ransom Everglades and Carrollton schools, with a $3–5 million sweet spot for single-family homes. Pinecrest offers large suburban lots, top-rated public schools, and a quieter pace for buyers prioritizing land over density. Key Biscayne provides controlled island living with beaches, parks, and a level of privacy difficult to match at comparable price points in Brooklyn or Westchester, with waterfront properties frequently exceeding $5 million. For families buying a second home in Miami before committing to a full move, Key Biscayne’s self-contained character makes it a natural first step.
What does it actually cost to own luxury real estate in Miami?
Many New Yorkers assume Miami is simply cheaper across every line item. The full picture is more nuanced, and buyers who ignore the recurring costs end up surprised in year two. The income tax math still wins decisively for high earners, but the insurance situation requires honest budgeting.
Property taxes, HOA fees, and the income tax math
Miami-Dade property taxes run roughly 0.9–1.1% of assessed value annually. On a $5 million home, that is approximately $45,000–$55,000 per year, comparable to what a Manhattan luxury condo owner pays. HOA fees diverge more sharply: newer Brickell luxury towers average $1.00–$1.75 per square foot monthly, while comparable Manhattan luxury buildings commonly run $2.50–$6.00. A 3,000-square-foot unit in a Brickell tower might carry $36,000–$63,000 in annual HOA costs, versus $90,000–$216,000 for the same square footage in a Manhattan luxury building (the upper end reflects ultra-luxury or full-service white-glove buildings). Factor in the income tax savings: New York’s combined state and city rate approaches 15% for top earners. For a high-income professional, that annual delta frequently exceeds $100,000, and in many cases far more. The Florida tax advantages for New Yorkers making this move are not marginal, they are structural.
Insurance is the wildcard: what waterfront buyers need to know
A $5 million Miami waterfront home can carry $15,000–$35,000 or more in annual insurance premiums, compared to $4,000–$10,000 for a comparable New York property. Hurricane, windstorm, and flood coverage are often separate line items with high deductibles, and older condo buildings may face special assessments that add significant one-time costs. This is a due-diligence requirement, not a deal-breaker, but it must enter the budget before you fall in love with a unit. When the income tax savings are factored in, most high earners still come out well ahead.
Financing Miami luxury real estate for New Yorkers
New York residency is not the financing obstacle. Florida lenders focus on property type, occupancy classification, loan size, income, and post-closing reserves. The conforming loan limit for most Florida counties sits at approximately $832,750 in 2026; anything above that is jumbo, and the luxury market sits comfortably in jumbo and super-jumbo territory. Current 30-year fixed jumbo rates in Florida range from approximately 6.875% to 7.54%, depending on lender, credit profile, and points paid at closing.
Jumbo loans, portfolio lending, and down payment expectations
For well-qualified buyers, jumbo loans up to roughly $1.5 million may require as little as 10% down with strong credit and reserves. Larger balances typically require 20–25%, and some lenders ask for 30% on investment properties. Credit minimums commonly run 700–720, with 740 preferred on larger loans. Reserve requirements range from 6 to 24 months of PITI depending on loan size and property type. Portfolio and private-bank loans are the right tool for buyers with complex income structures: equity compensation, partnership distributions, trust income, or large liquid assets relative to earned income.
Second home vs. primary residence: how occupancy changes the deal
A Miami pied-à-terre used seasonally is underwritten as a second home, with higher reserves and stricter ratios than a primary residence. Buyers planning a full relocation should document the move clearly: Florida occupancy intent, disposition of the New York property, and employment continuity. Planned rental use triggers investment property underwriting, which tightens qualification criteria further and typically requires 25–30% down.
What should New Yorkers budget for the relocation itself?
The purchase is one line item. The move is another. A full-service three- to four-bedroom relocation from New York City to Miami runs $6,000–$12,300 for transportation alone, before packing, vehicle shipping, storage, or staging. Full family relocations with packing, vehicle shipping, staging, and concierge coordination routinely reach $25,000–$50,000. Any realistic New York to Miami relocation guide has to treat these costs as fixed budget items, not afterthoughts.
Moving, storage, and vehicle costs
Full-service interstate moves for a two-bedroom unit run $3,800–$8,900 before packing add-ons or elevator fees. Vehicle shipping adds $500–$1,200 per car. Storage-in-transit runs $100–$300 monthly. Moving during peak summer months (May through September) adds roughly 15–30% to the base quote, and New York building certificate-of-insurance requirements can delay a scheduled move by days. Book an off-season window if the purchase timeline allows it.
Legal, tax, and domicile planning before you leave New York
New York State audits domicile changes aggressively, commonly examining the one to three tax years after the claimed move. To successfully establish Florida domicile, you need to: abandon your New York home as your primary residence, obtain a Florida driver’s license, register to vote in Florida, file a Declaration of Domicile with the county clerk, and keep New York days below 184 in the calendar year. Hiring a tax attorney or CPA to document the domicile switch typically costs $1,000–$5,000. A Florida real estate attorney for contract review and closing assistance adds another $500–$2,500. Budget these before the move, not as an afterthought.
Why New Yorkers work with Andres Jara to buy Miami luxury real estate
In the agent’s experience working with relocating buyers, most New Yorkers arrive in Miami applying Manhattan’s market logic: broker relationships, attorney review periods, co-op board dynamics, and per-floor comp analysis by address. Miami’s market works differently at the building level, and that mismatch costs money and time when buyers navigate it without local expertise.
Andres Jara | South Florida Luxury Real Estate offers a specific and measurable advantage here. The practice operates a building-level research covering buildings across South Florida neighborhoods, refreshed daily. A New Yorker evaluating Miami luxury condos across three towers in Brickell gets unit-level inventory, closed-sale history within each specific building, floor plan and stack comparisons, and absorption rates for that tower rather than a neighborhood average. That is the same granularity an institutional buyer would commission a research firm to produce, delivered through a single agent affiliated with Douglas Elliman’s luxury network, one with a consistent record of 5-star client reviews.
With 24 years of South Florida experience and bilingual English/Spanish service, Andres Jara also handles the cultural translation that Manhattan buyers need: faster contract timelines, developer-direct relationships, off-market inventory access, and building-specific pricing dynamics that require genuinely local knowledge to navigate. Whether the purchase is a Brickell pied-à-terre or a Sunny Isles oceanfront residence, the process runs cleaner when your agent speaks the language of the market, and in some cases, literally speaks the seller’s language.
The bottom line on Miami luxury real estate for New Yorkers
Miami luxury real estate represents a genuine financial and lifestyle upgrade for New Yorkers when approached with the right data. The price-per-square-foot gap is real and documented in 2026 closed sales. The income tax math is decisive for high earners. The neighborhoods offer genuine equivalents to major New York lifestyle profiles: Brickell for Manhattan-density energy, Coral Gables for Upper East Side refinement, and Key Biscayne for island-level privacy.
The costs to watch: insurance, condo assessments, and proper domicile documentation. None of these are deal-breakers. All of them are manageable with preparation and the right professional team. The buyers who get hurt in this market are the ones who tour three buildings on a weekend trip and make an offer without understanding unit-level pricing history.
If you are considering miami luxury real estate for new yorkers as a primary relocation or a second home in Miami, start with building-level data behind every recommendation. Reach out to Andres Jara | South Florida Luxury Real Estate directly. A focused conversation about your budget, timeline, and lifestyle goals is the fastest way to turn a Miami interest into a confident purchase decision.
Frequently Asked Questions
How large an insurance premium should I budget for a $5 million waterfront Miami home?
Budget roughly $15,000–$35,000 or more per year for a $5 million Miami waterfront home. Hurricane, windstorm, and flood coverage are often separate line items with high deductibles, and older condo buildings may face special assessments that add significant one-time costs.
What steps do I need to take to establish Florida domicile for tax purposes?
You must abandon your New York home as your primary residence, obtain a Florida driver’s license, register to vote in Florida, file a Declaration of Domicile with the county clerk, and keep New York days below 184 in the calendar year. Hiring a tax attorney or CPA to document the domicile switch typically costs $1,000–$5,000, and a Florida real estate attorney for contract review and closing assistance adds another $500–$2,500.
How much down payment will lenders expect on a Miami luxury property?
Expect 10% down on jumbo loans up to roughly $1.5 million for well-qualified buyers, 20–25% for larger balances, and 30% for many investment properties. Credit minimums commonly run 700–720 with 740 preferred on larger loans, and reserve requirements typically range from 6 to 24 months of PITI depending on loan size and property type.
Can I get a Florida mortgage while still living in New York?
Yes, New York residency is not an obstacle to financing in Florida. Lenders focus on property type, occupancy classification, loan size, income, and post-closing reserves rather than current state residency.